Paid in Full: Debt Free Date
Mira tu fecha sin deudas, lo que cuestan los intereses y comisiones, y sigue cada pago.
- IOS
- ANDROID
- Utilidad
- Disponible


Sobre Paid in Full
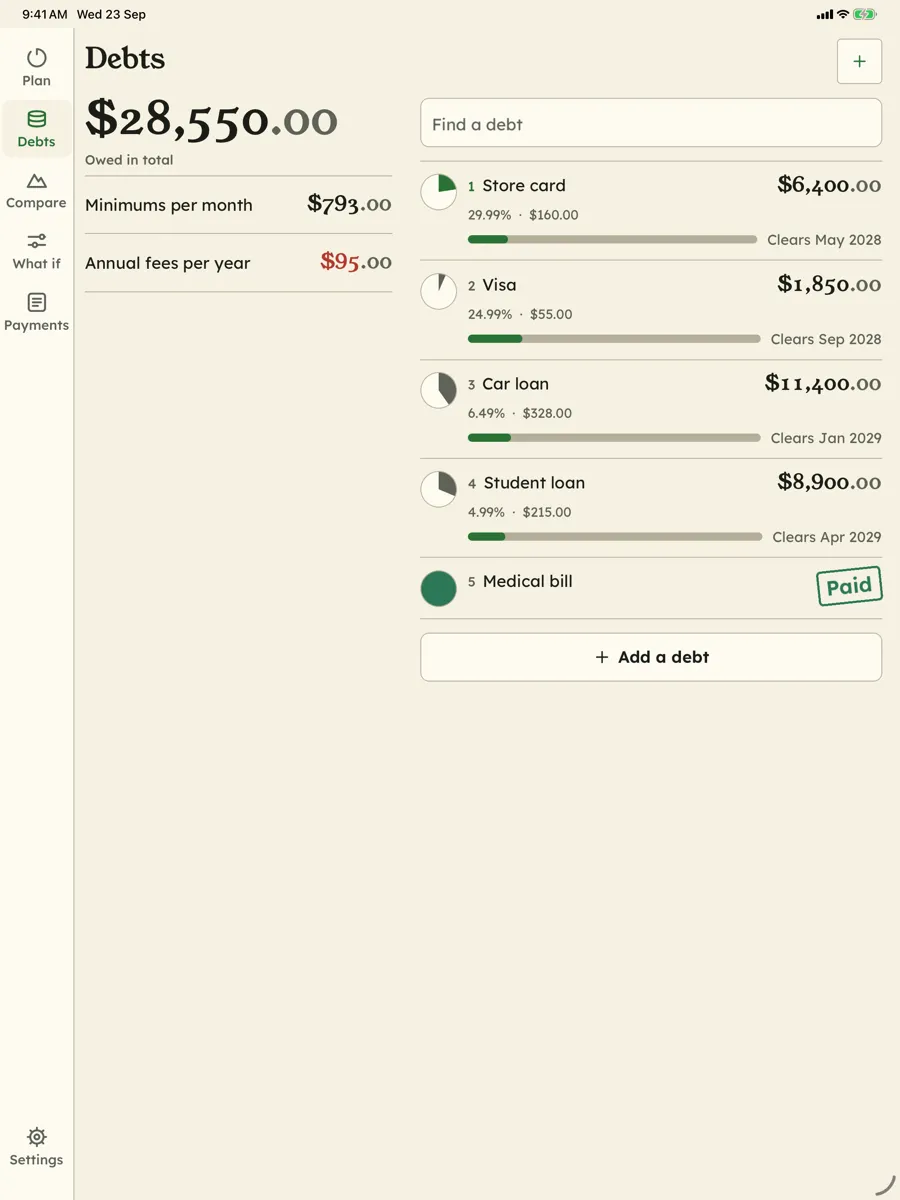
Escribe lo que debes —saldo, interés, pago mínimo y cualquier cuota anual o recargo— y Paid in Full te responde con el mes en que quedarás sin deudas. Te muestra lo que cuesta la deuda: los intereses de este mes, los intereses y comisiones por delante y cómo se compara tu plan con pagar solo los mínimos, por deuda y en total. Mueve un deslizador de pago extra y mira cómo se mueve la fecha. Compara bola de nieve y avalancha lado a lado. Anota pagos, y los intereses y comisiones de tus extractos, y sigue el plan frente a lo que de verdad pasó, con hitos y un historial de cada cambio de la fecha. Sin acceso al banco ni cuenta: todo se queda en tu dispositivo. Estimaciones, no asesoramiento financiero.
Características
Tu fecha sin deudas, en primer plano
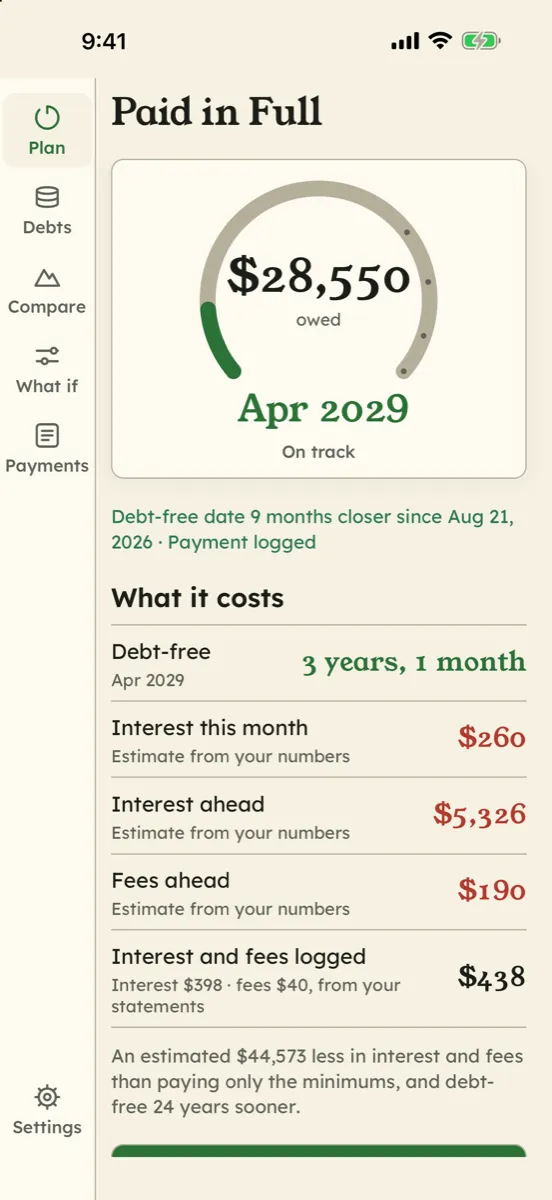
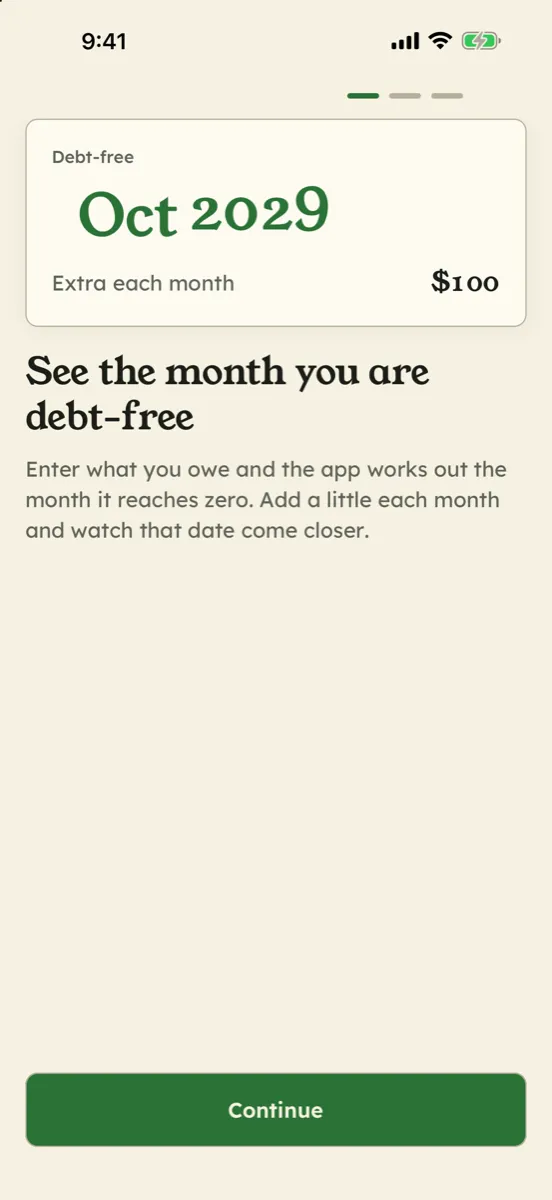
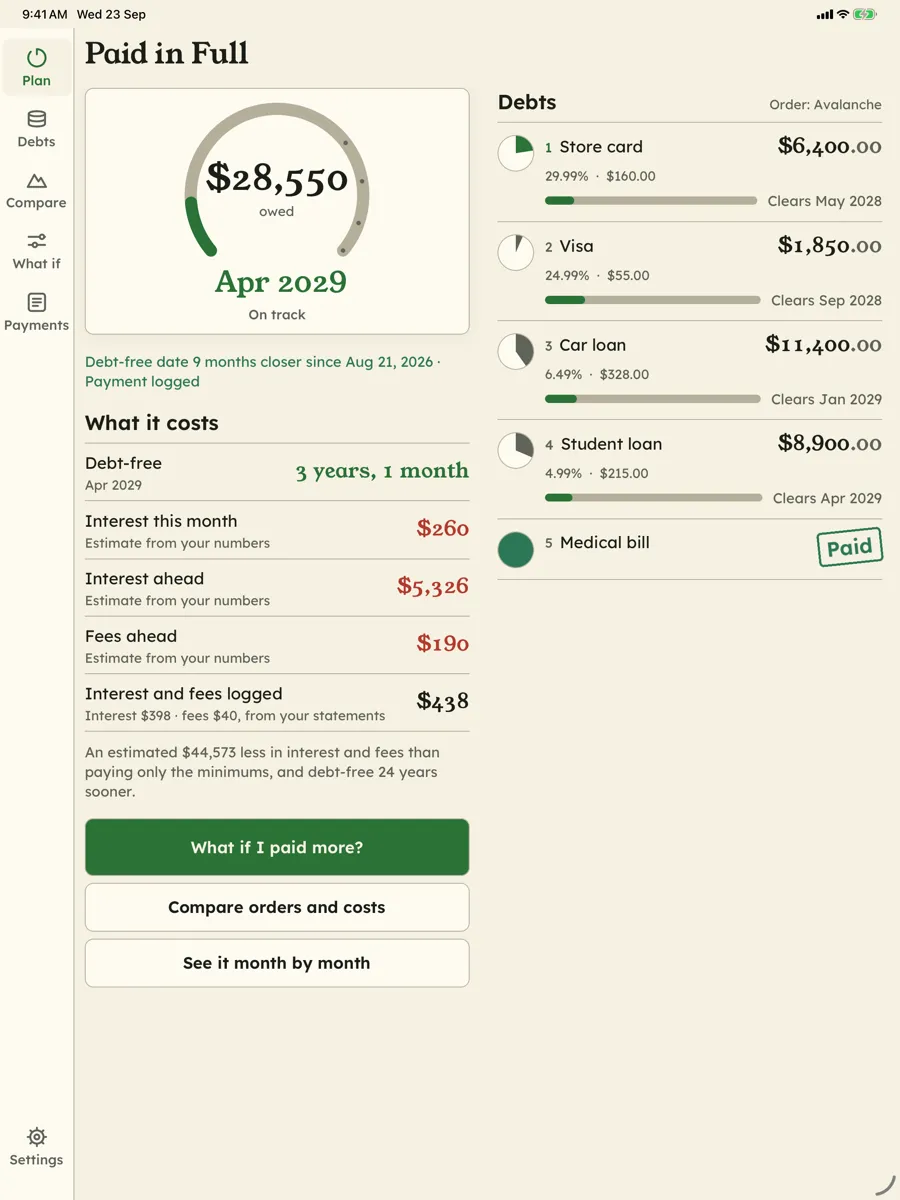
La página Plan responde con un mes —cuando tu último saldo llega a cero— dentro de un anillo que se llena a medida que bajan las deudas, con la última vez que esa fecha se movió y el motivo escritos justo debajo
Lo que te cuesta la deuda
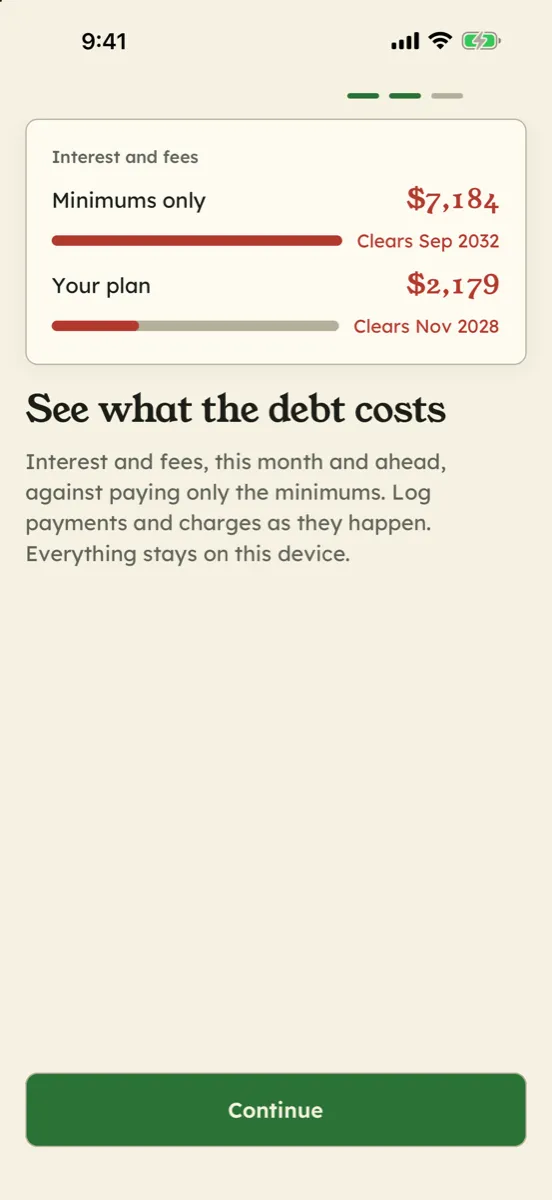
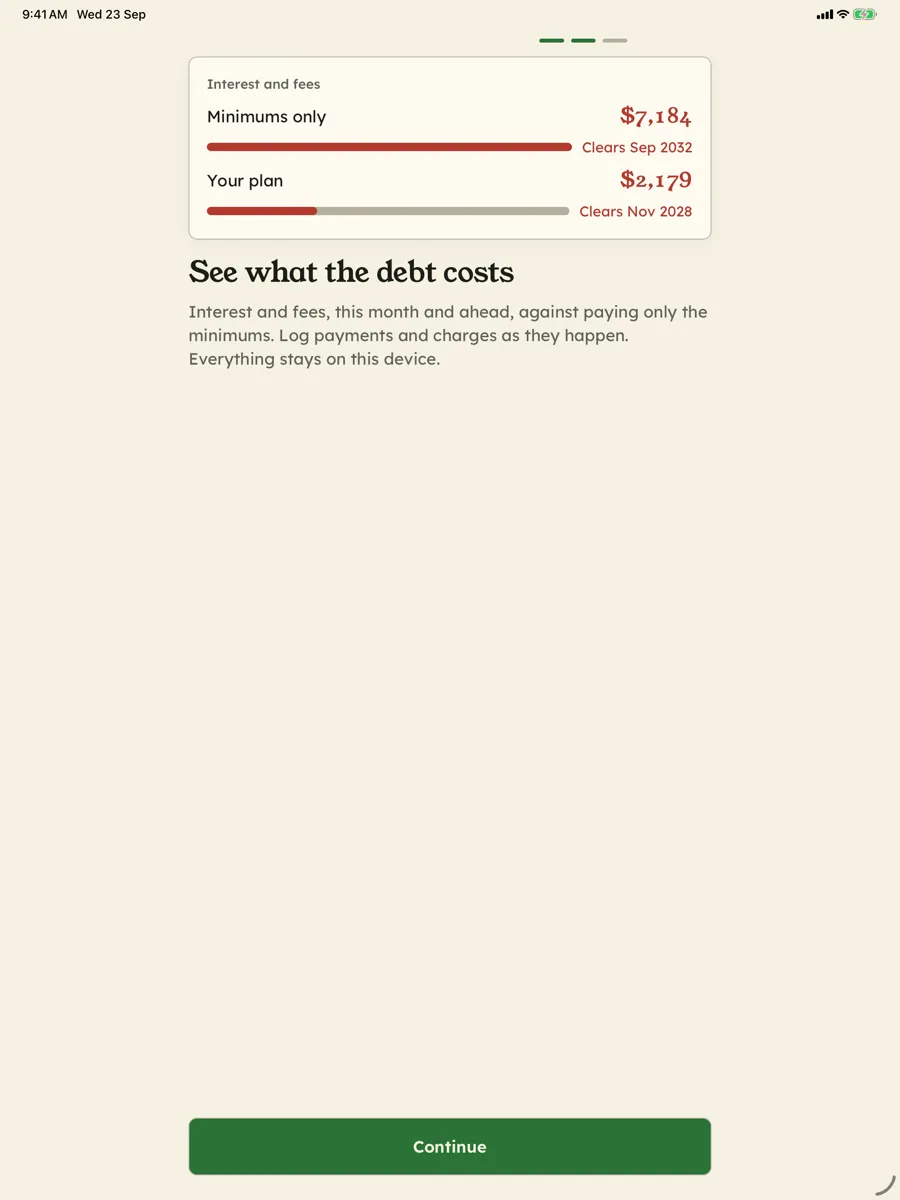
Los intereses de este mes, los intereses y comisiones que aún quedan por delante, y los intereses y comisiones que anotaste de tus extractos. La cuota anual de una tarjeta se cobra en su mes cada año que la deuda siga abierta, y las comisiones siempre se muestran aparte de los intereses. Todo etiquetado como lo que es: una estimación
Tu plan frente a pagar solo los mínimos
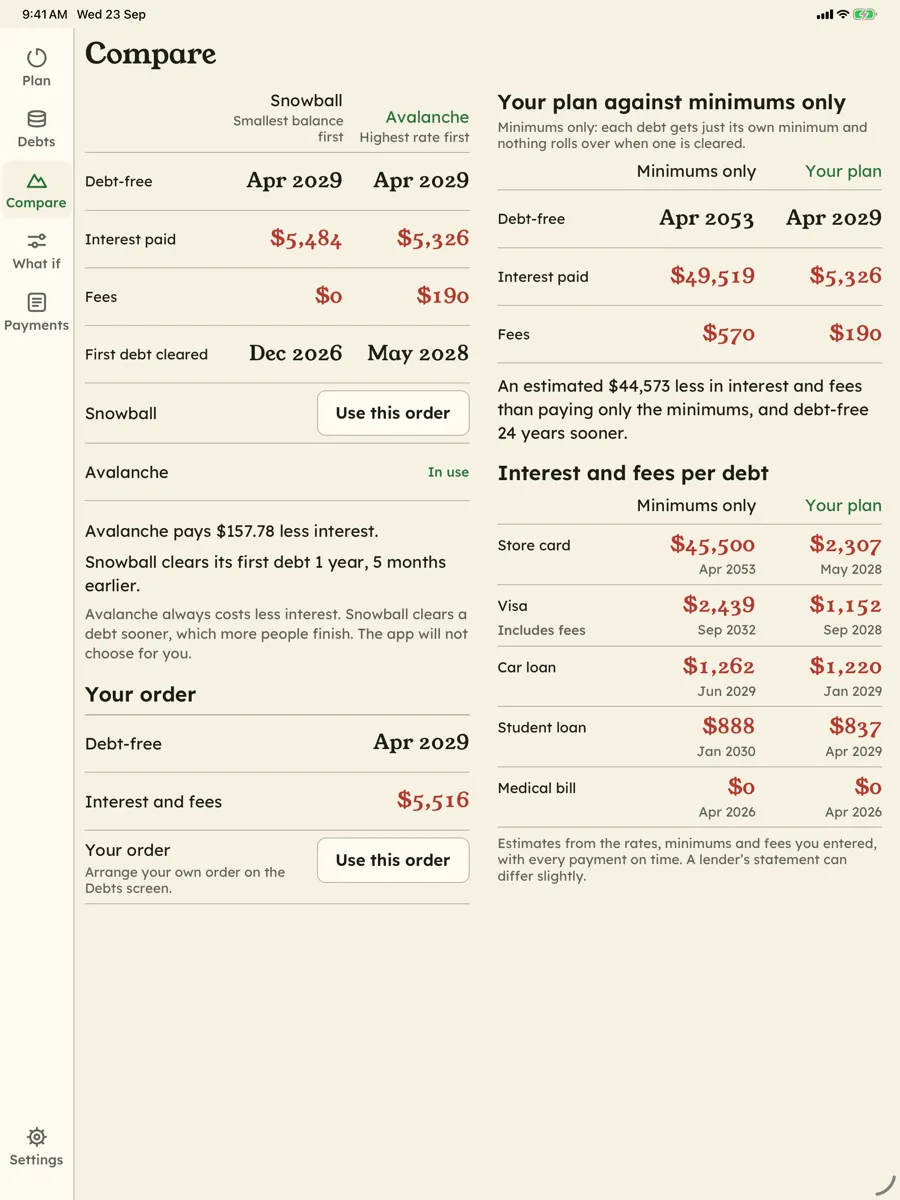
Mira lo que costaría en intereses y comisiones pagar solo los mínimos, por deuda y en total, y cuántos meses más tardarías en terminar, junto al plan que de verdad sigues
Bola de nieve, avalancha o tu propio orden
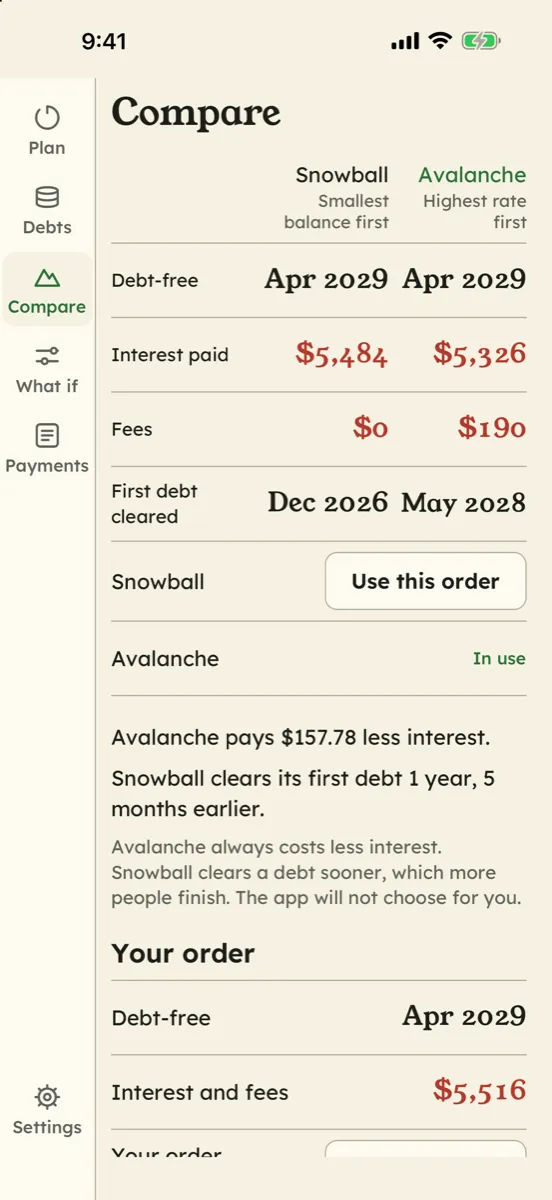
Primero el saldo más pequeño frente a primero la tasa más alta, lado a lado con el mes sin deudas, los intereses, las comisiones y la primera deuda saldada. Se explica con claridad qué ganas y qué pierdes con cada uno, y la app no elige por ti
Sigue cada pago y cada cargo
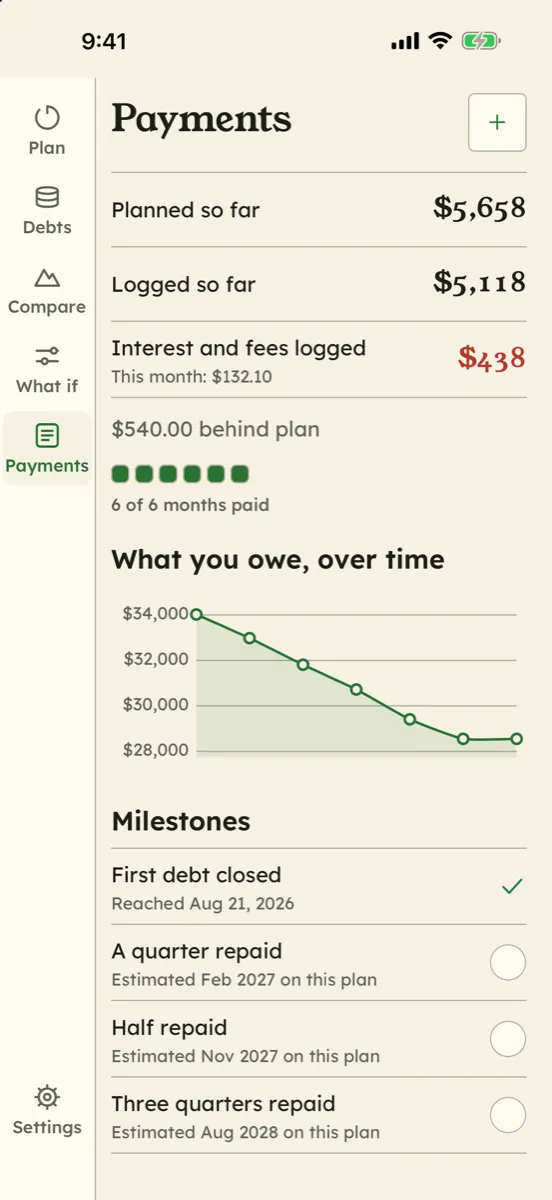
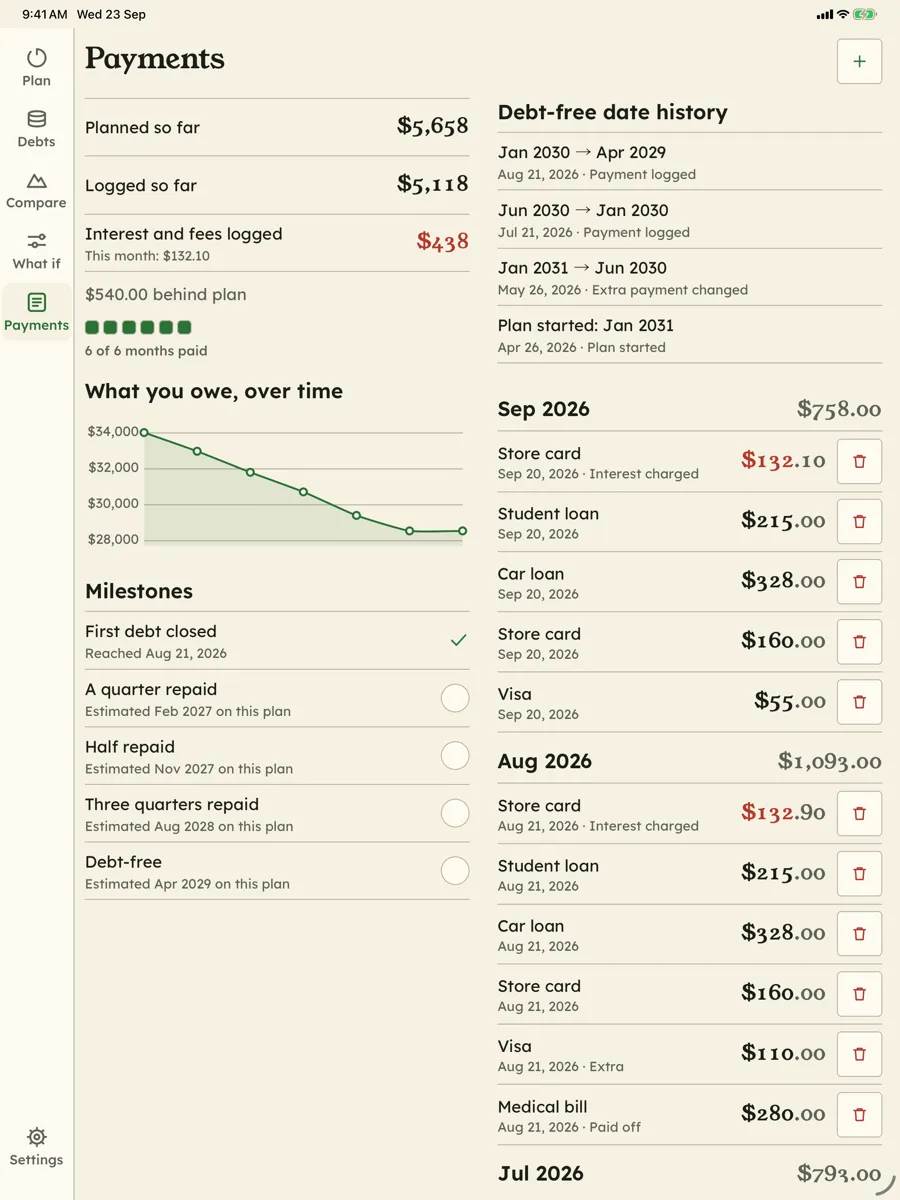
Anota pagos, y los intereses y comisiones de tus extractos. Sigue el plan frente a lo que de verdad pasó, con barras de progreso, un gráfico de lo que debes, hitos —primera deuda cerrada, un cuarto, la mitad, tres cuartos— y un historial de cada cambio de la fecha
Tus datos se quedan en tu dispositivo
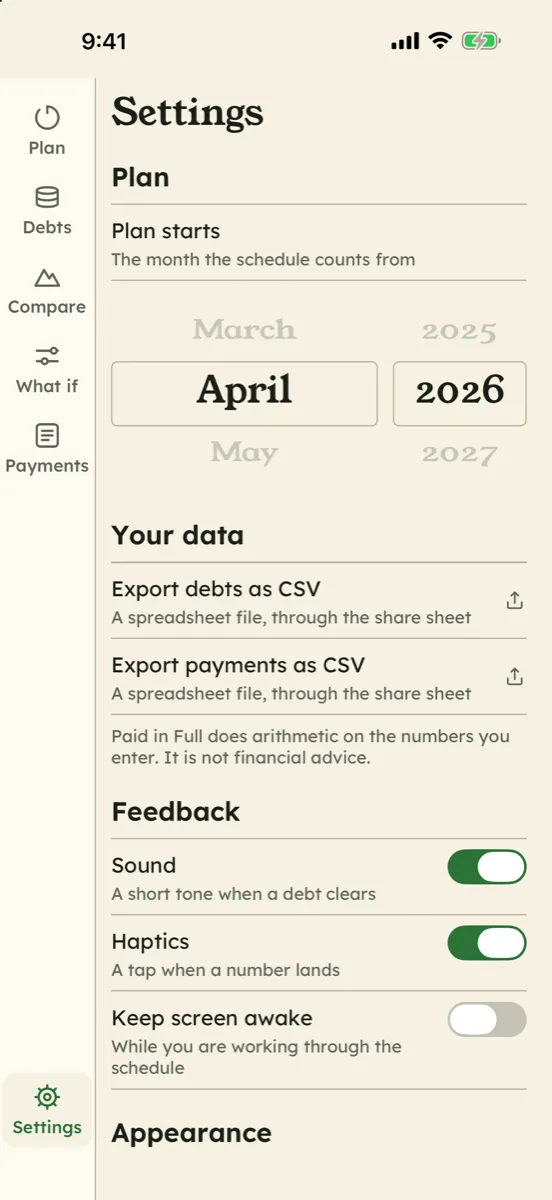
Sin acceso al banco, sin cuenta, sin servidor. Exporta tus deudas, tus pagos y el calendario completo en CSV, y borra todo desde Ajustes en un solo paso. Todo se calcula en centavos enteros, cuadrado al centavo
Capturas
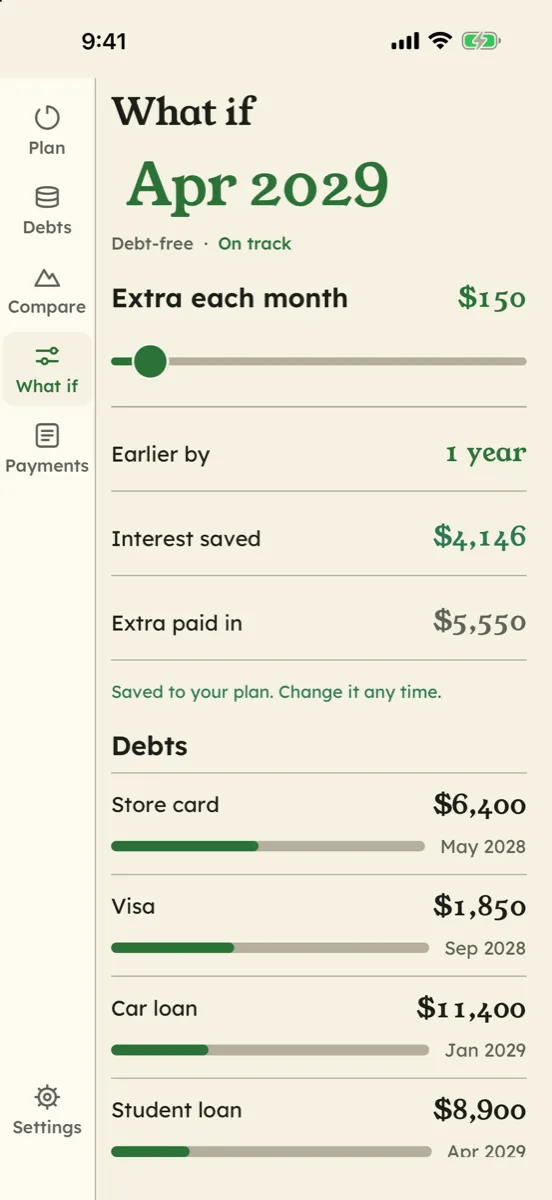
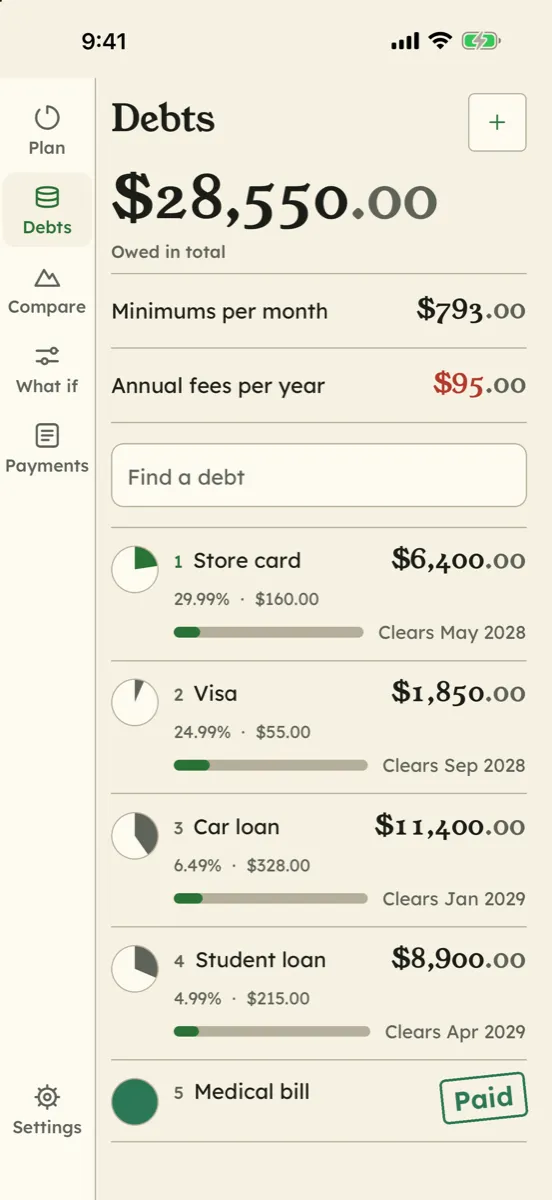
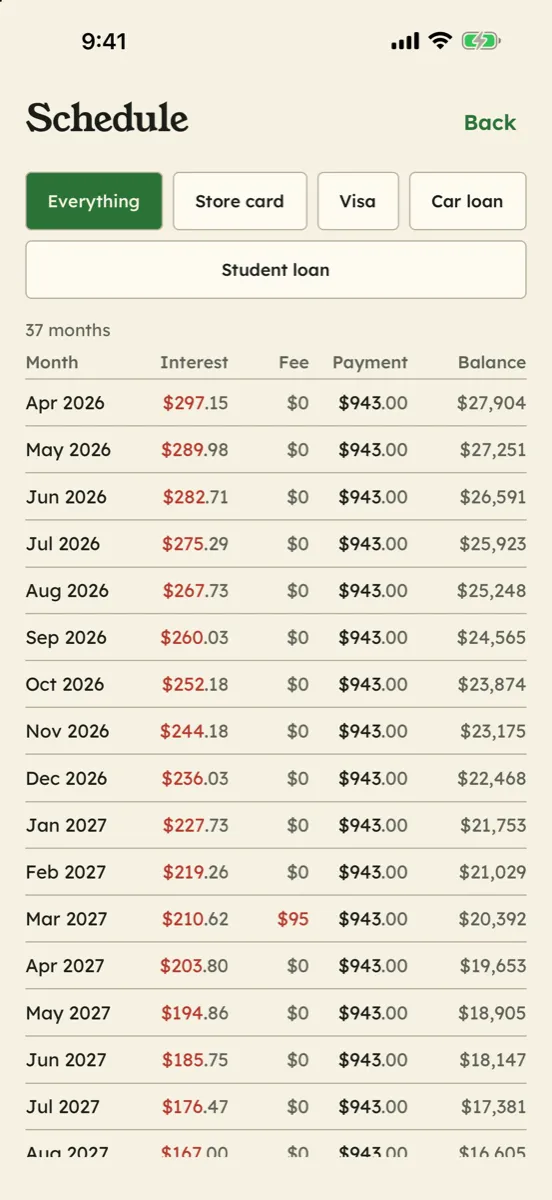
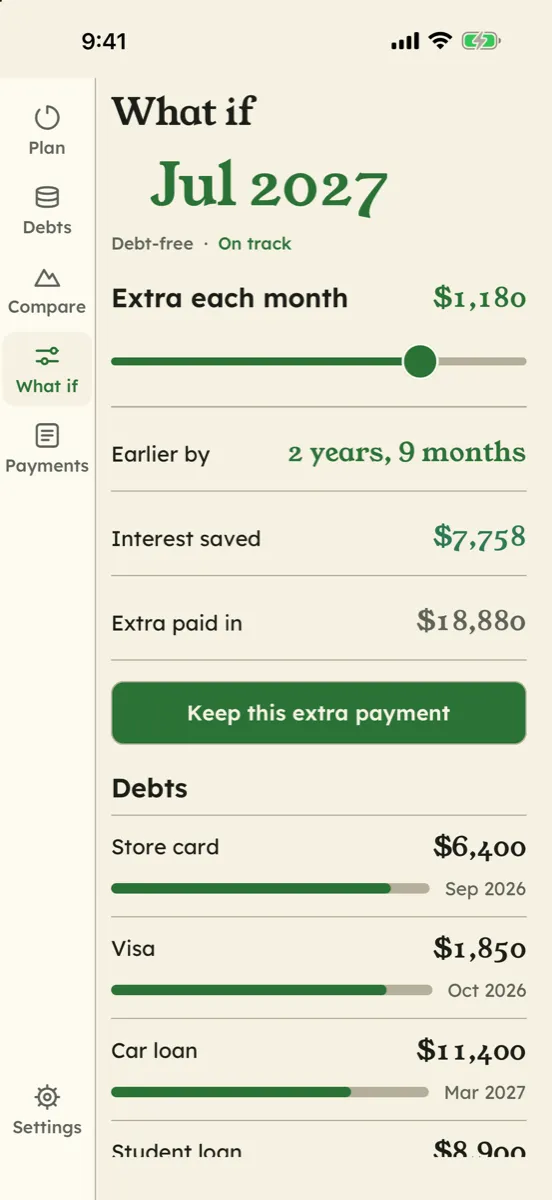
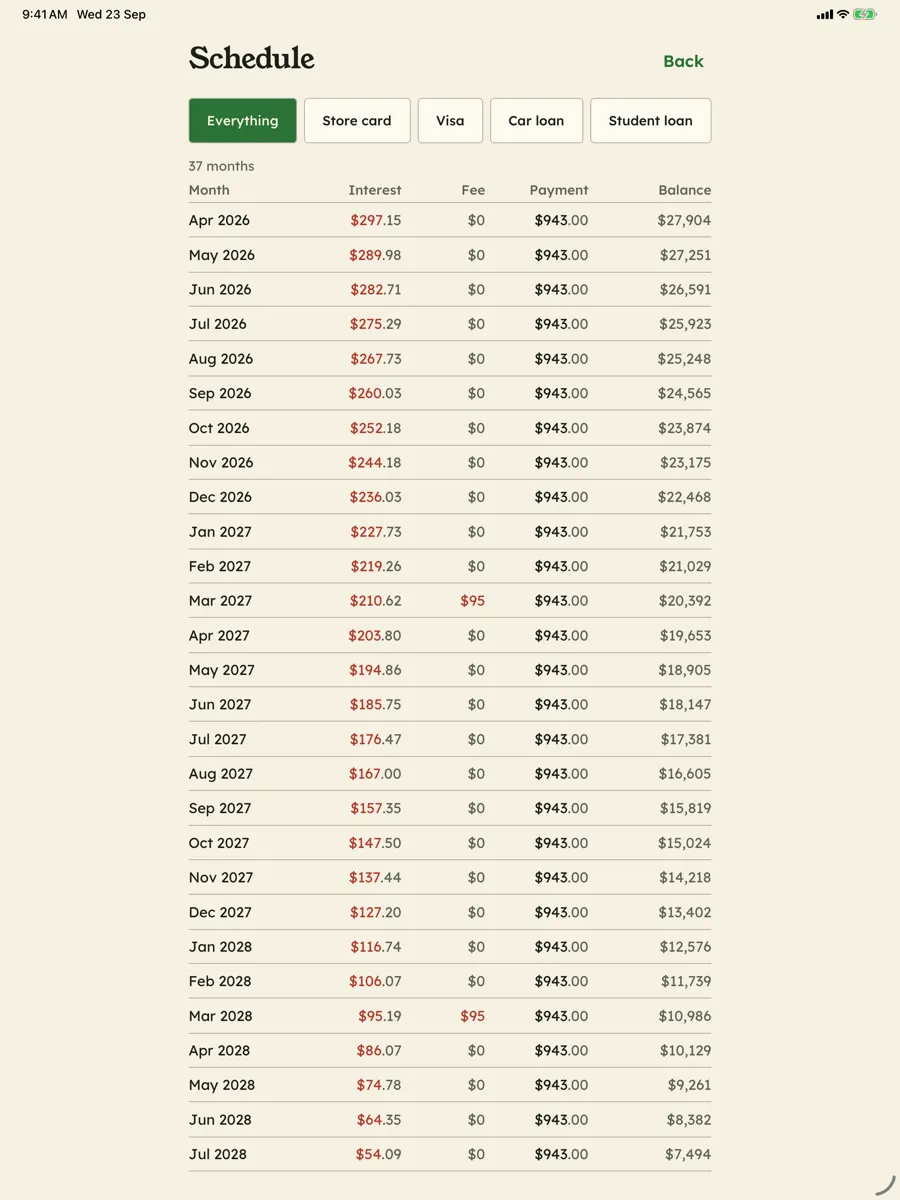
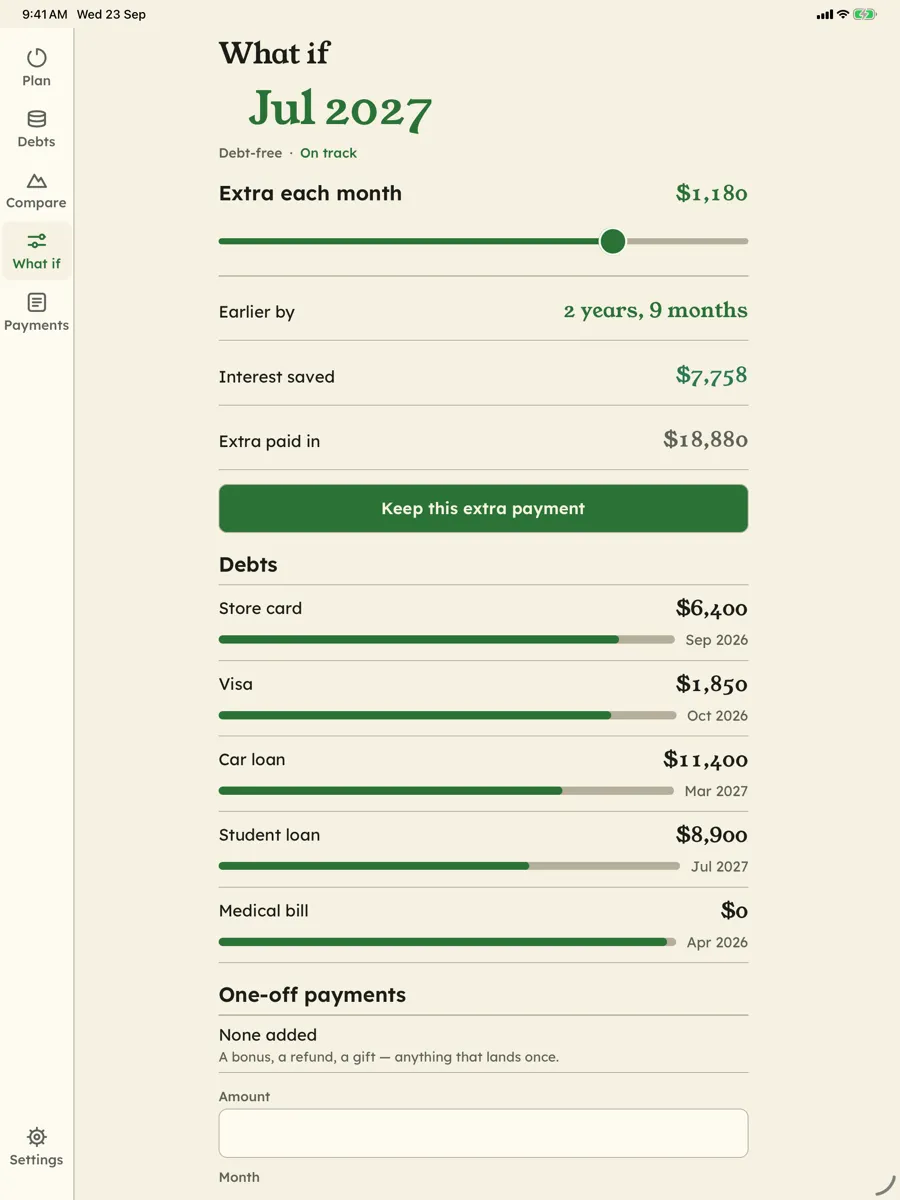
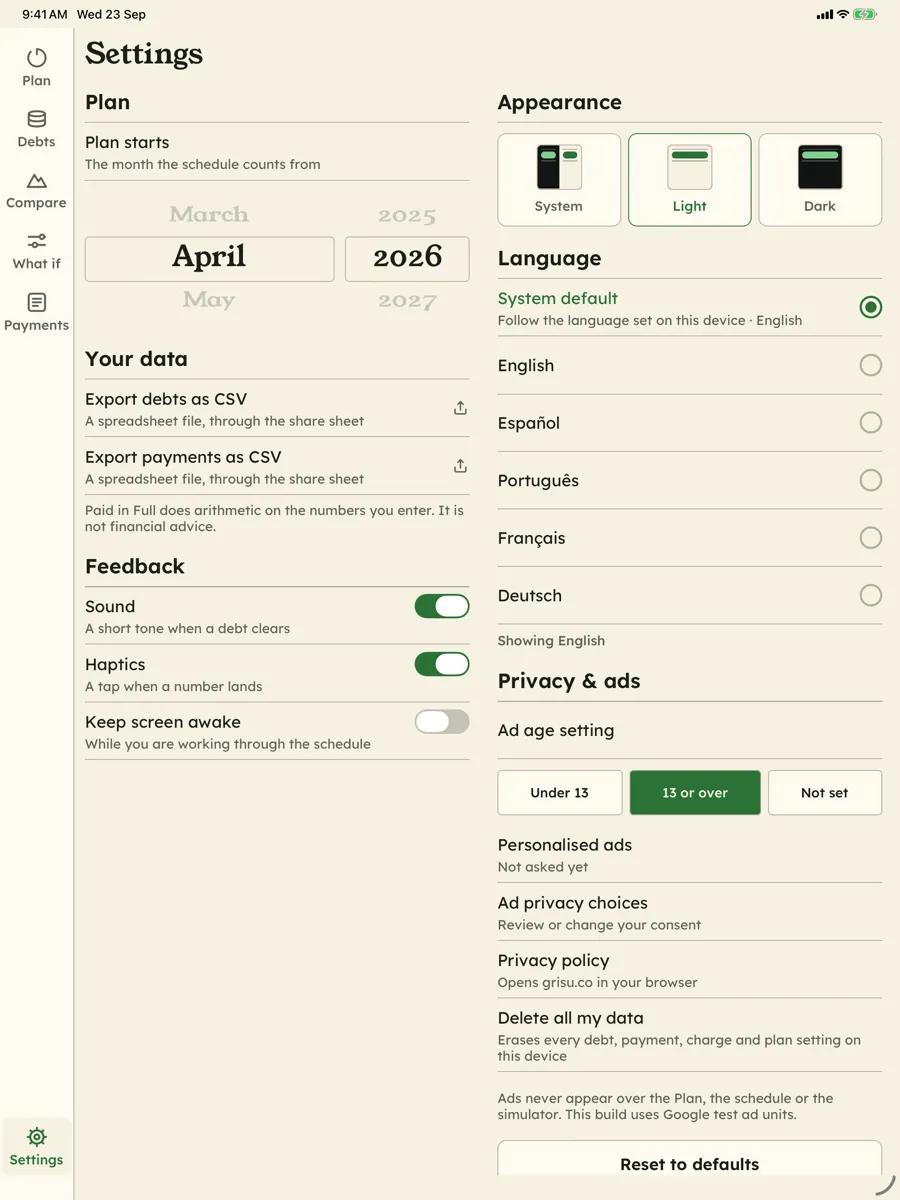
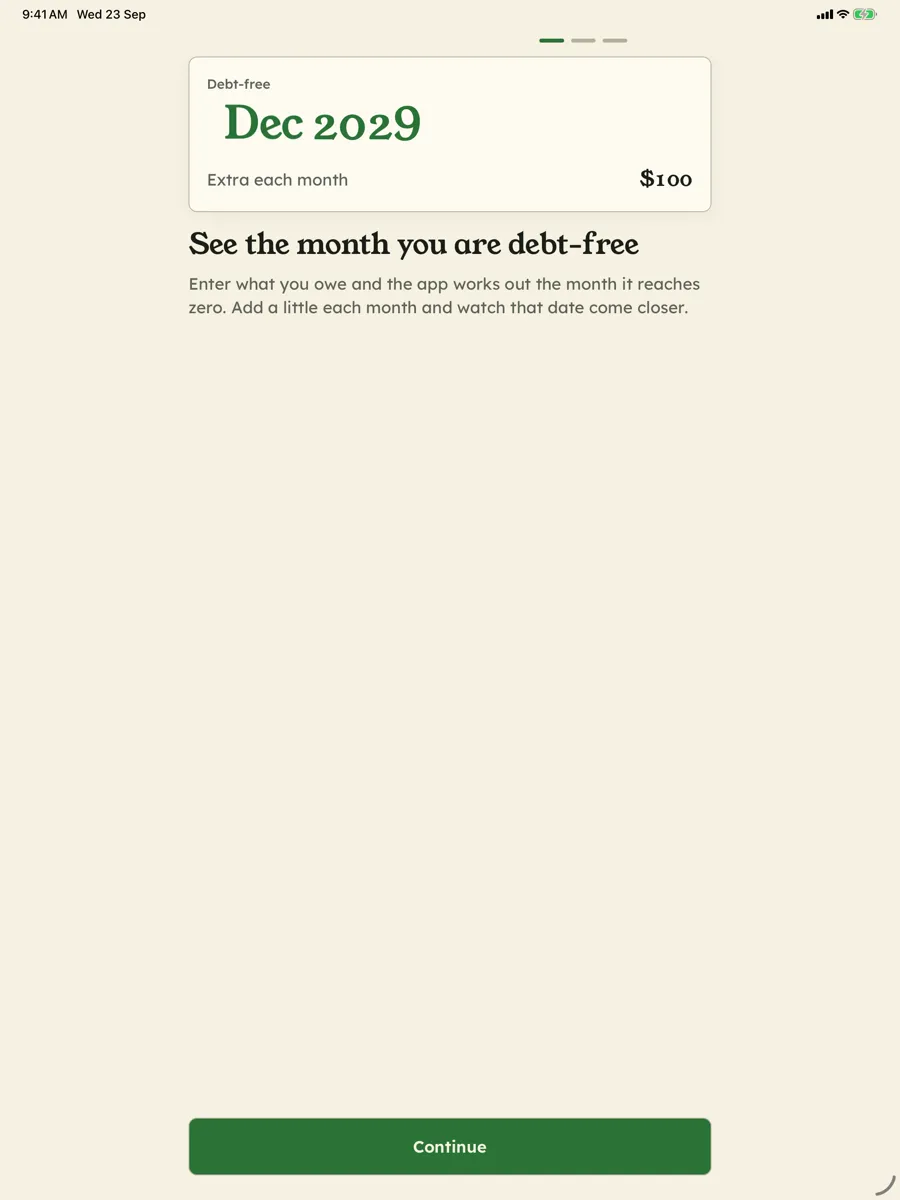
El texto detallado que sigue aún no está traducido y se muestra en inglés.
About Paid in Full
Most debt apps answer a question nobody asked: how much do you owe? You already know that — it is the number you avoid looking at. Paid in Full answers the one you actually want answered, when does this end, and what is it costing me?, and then lets you push that date around.
Enter each debt: name, balance, interest rate, minimum payment, currency, and — if they apply — a promotional rate, an annual fee and a late fee. The Plan page replies with a single month inside a ring that fills as your debts come down, and under it, the last time that month moved and what moved it.
What it costs, in two numbers, never one
Interest and fees are different things, and a single “cost” figure hides the one you can often do something about. So the app keeps them apart everywhere: interest this month, interest still ahead, and fees ahead — a card’s annual fee is charged in its month, every year the debt is still open. Copy the interest and fees off your statements into the payment log and the app keeps a running total of what the debt has actually cost you so far.
Then it puts your plan next to the one you are on without a plan: paying only the minimums, where each debt gets its own minimum and nothing rolls over when one is cleared. Interest and fees on each, per debt and in total, and how many months apart they finish. Every figure is an estimate from your numbers, and the page says so.
Why the simulator is the whole app
The date on its own is information. The date moving is the product.
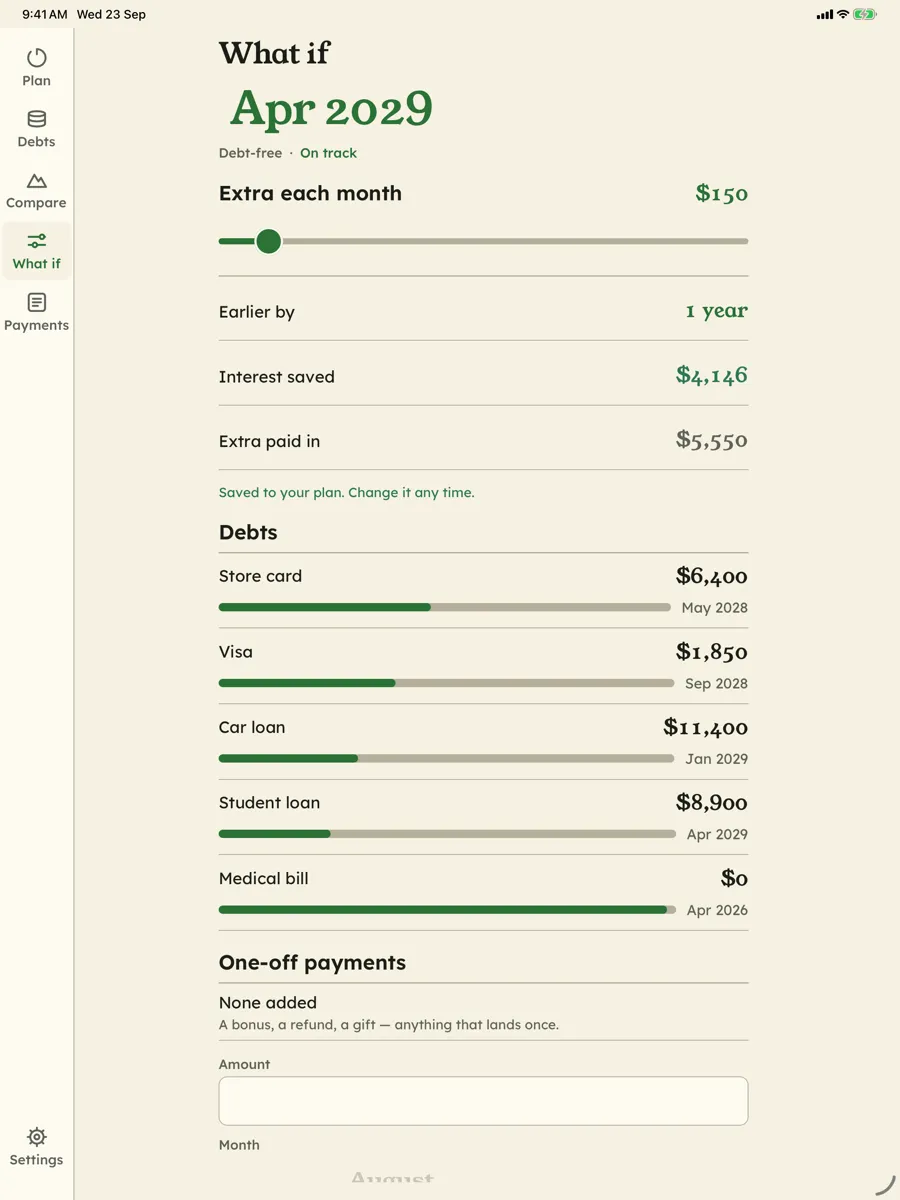
Drag the extra-payment slider and the entire schedule recomputes on every frame: the date rolls to its new month, the months saved count up, the interest you would not pay falls. Drop a one-off payment into a future month — a bonus, a tax refund — and see exactly what it buys.
There is no better argument for skipping something than watching what skipping it is worth, in months. Not “you shouldn’t”, but “that is eleven weeks”. You may still decide it is worth it; at least you decided knowing the price.
Snowball, avalanche, and why the app refuses to choose
Snowball clears the smallest balance first, so a whole debt disappears sooner. Avalanche pays the highest rate first, and is arithmetically the cheapest ordering of a fixed monthly pool — always. Paid in Full shows both side by side, with their debt-free month, interest, fees and first debt cleared, and states the trade-off out loud: avalanche costs less interest, snowball is more often finished.
The app does not pick one for you, and that is deliberate. You know things about yourself that a payment schedule does not. So there is a third option: arrange them in whatever order you like. There is no “recommended” badge anywhere in the app, and the code carries a comment saying there must never be one.
Tracking, without the scolding
Log what you actually paid and see a signed number — ahead of plan, or behind — with no streaks, no grades and no red banners. Being behind is the normal case, and an app that treats it as failure gets deleted in exactly the month you needed it.
What the log does give you is a record worth opening: progress bars per debt, a chart of what you owe over time, milestones as they arrive — the first debt closed, a quarter, half and three quarters repaid, debt-free — each with the day it happened or the month the plan expects it, and a history of every time your debt-free date moved, from what to what, and why.
The screen we did not soften
If a minimum payment does not cover a month’s interest, the balance grows and no schedule ever finishes. That is not an exotic input; it is an ordinary credit card in a bad year.
Paid in Full reports it. It says the plan never pays off and names the debts that are growing, rather than grinding out a comforting date ninety years away.
Arithmetic you can check
Every amount is a whole number of minor units: cents, pence, yen. There are no floating-point numbers anywhere in the money path. The rounding rule is stated once and tested: half-up, once per month, on exact integers — what a statement does — and tests assert that money paid in equals principal plus interest plus fees, to the cent.
The engine’s other choices are opinions, and the code says so: a simple monthly rate of APR ÷ 12 rather than daily compounding, interest rounded monthly, a payment order fixed for the whole plan, every payment on time. Each is defensible, and each will differ slightly from some lender’s arithmetic. This schedule is a model. Your lender’s statement is the authority.
What it is not
Paid in Full computes arithmetic on numbers you typed in. It is not financial advice: it never recommends consolidating, refinancing, or which debt to pay first — it presents the comparison and you choose. And it has no bank connection of any kind: no linking, no imports, no credentials, and no technical ability to acquire any.
Free, with a small ad
Every feature is free. A banner on the Debts and Settings screens pays for it, and now and then a full-screen ad after you save a payment — never over the Plan, the schedule or the simulator, and never after a payment that clears a debt. Nothing is sold: there are no in-app purchases.
Privacy, plainly
- No account, no server, no bank connection. Your debts are in a database on your phone. We do not have a copy and have no way to get one.
- No analytics, no crash reporting of ours. We cannot see how you use the app — there is nowhere for that data to go.
- Ads, disclosed. Google AdMob ads on the Debts and Settings screens. Consent is requested where the law requires it; on iOS, Apple’s tracking prompt comes only after a short explanation, never at launch; ad content is capped below the adult categories regardless.
- Get your data out, or erase it. CSV export of the debts, the payments and charges, and the full schedule, handed to the system share sheet; Settings → Privacy & ads → Delete all my data erases everything on the device.
Full detail is in the privacy policy.


Más apps como Paid in Full
-

Aubade: Daily Affirmations
Una frase al día, sobre papel y en tu pantalla de inicio.
-

Valise: Trip Planner & Split
El plan, el mapa y el dinero de un viaje, en una maleta en tu teléfono.
-

Quadrille: QR Scanner & Maker
Códigos QR como objetos de diseño: dales estilo, escanéalos, guárdalos.
-

Subledger: Subscription Log
Todo lo que se renueva, sin conectar con tu banco.